
Tax administration is becoming increasingly digital, and e-invoicing is an important part of this shift. For business leaders, invoicing can no longer be viewed only as an accounts payable or accounts receivable process.
Invoice data can affect tax reporting, financial controls, audit readiness, cash flow and the quality of information available to management.
Qatar's General Tax Authority (GTA) has been developing its digital tax infrastructure, including an e-invoicing project, as part of a wider effort to integrate electronic tax services and financial information. (General Tax Authority)
Now is the right time for businesses to understand what e-invoicing could mean for their finance and tax processes, and to assess whether their systems, data and controls are ready.
Chapter 1
Understanding Tax E-Invoicing
What e-invoicing means, where Qatar's framework currently stands, and how it relates to VAT.
What is tax e-invoicing?
Tax e-invoicing is the electronic creation, exchange and processing of invoices in a structured digital format that can support automated financial and tax processes.
A traditional invoice is typically created as a document and sent to a customer by email or another channel. An e-invoice is built around structured data that accounting systems can process electronically and, where applicable, exchange with tax administration platforms.
For finance leaders, the significance goes beyond replacing paper or PDF invoices. The quality, completeness and consistency of invoice data influence every downstream financial and tax process.
The connected invoice flow
A connected e-invoicing environment links each stage of a transaction:
- Sales The commercial transaction agreed with the customer.
- Invoice Structured invoice data generated from the transaction.
- Accounting The invoice recorded in the general ledger.
- Tax Transaction data captured for tax compliance.
- Reporting Information reflected in management and statutory reports.
- Audit A traceable record that supports review and assurance.
This creates a more consistent flow of transaction information across the business.
Where does e-invoicing in Qatar currently stand?
The move toward e-invoicing forms part of a broader digital transformation of tax administration. The General Tax Authority has publicly referred to its e-invoicing project as part of efforts to develop digital tax systems and improve the integration of financial and tax information.
On 6 May 2026, Qatar's Council of Ministers approved a draft law on electronic invoicing and its executive regulations, prepared by the Ministry of Finance in coordination with the General Tax Authority.
A draft law approved by the Cabinet is an important step, but it is not yet a binding obligation. The draft must complete the legislative process and be published in the Official Gazette, and details such as the businesses and transactions in scope, the technical specifications and the implementation timeline are expected to be confirmed with the final law and regulations.
| Development | Position at the time of writing |
|---|---|
| E-invoicing project | Underway, led by the General Tax Authority |
| Draft e-invoicing law and executive regulations | Approved by the Council of Ministers on 6 May 2026 |
| Final law published in the Official Gazette | To be confirmed |
| Businesses and transactions in scope | To be confirmed |
| Technical requirements and effective dates | To be confirmed |
This distinction matters for CFOs and finance teams making technology and process investments. The right approach is to prepare for the direction of regulation without making assumptions about requirements that have not yet been formally established.
How does e-invoicing relate to VAT?
E-invoicing and VAT are separate regulatory matters and should not be treated as the same issue.
The General Tax Authority states that VAT has not been applied in Qatar. (General Tax Authority) Businesses should therefore not assume that the development of an e-invoicing framework means VAT is in effect or has a confirmed start date.
Technology and process decisions should be based on confirmed regulatory requirements. Businesses should continue to monitor official announcements and assess the implications of each requirement separately.
What does e-invoicing change?
At its core, e-invoicing changes how invoice information is created, exchanged, processed and retained. Its impact can extend much further:
Finance
How transactions are recorded and reconciled.
Tax
How transaction information is captured and used for compliance.
Technology
How ERP, billing and other systems exchange information.
Data
How customer, supplier and transaction information is maintained.
Controls
How invoices are approved, changed and monitored.
Management
How quickly reliable financial information becomes available for decision-making.
This is why e-invoicing should be viewed as a business process and data transformation, not simply a finance system upgrade.
Chapter 2
What E-Invoicing Could Mean for Your Business
E-invoicing reaches well beyond the invoice itself, into finance, tax, technology, data, controls and audit.
E-invoicing is more than an invoice format
For a CFO, the important question is not simply whether the system can generate an electronic invoice. The more important questions are:
- Can our systems capture accurate transaction data?
- Does invoice information flow correctly into the general ledger?
- Can we maintain appropriate supporting records?
- Can we identify errors before invoices are issued?
- Can we reconcile invoices with accounting records?
- Can we retrieve information quickly when required?
- Can our finance and IT systems support future regulatory requirements?
- Can our people manage the new processes effectively?
These questions move e-invoicing beyond the accounts function and into business control, technology and data management. Six areas deserve particular attention.
1. Finance and accounting processes
Businesses should review how invoices are currently created, approved, issued, recorded, reconciled and reported. Particular attention should be given to:
- Customer and supplier master data
- Invoice numbering
- Transaction dates
- Amounts and currencies
- Tax-related information
- Credit and debit notes
- Adjustments
- General ledger integration
- Accounts receivable and payable
- Reconciliation controls
- Document retention
The objective is consistency between the underlying commercial transaction, the invoice, the accounting records and financial reporting. If information is wrong at the point of invoicing, the error can move into other systems and reports. Digitalization does not remove the need for financial controls; it makes data accuracy and process discipline more important.
2. Tax compliance
E-invoicing can create a more structured digital trail of commercial transactions. For tax teams, this can support transaction visibility, data consistency, reporting accuracy and compliance monitoring.
As digital tax services expand, businesses need to check whether the information held in their internal systems is consistent with the information used for tax reporting. Data quality therefore becomes an important part of tax readiness.
3. ERP and technology readiness
E-invoicing should not be treated as a standalone software purchase. CFOs and CIOs should consider how future requirements could interact with:
- ERP systems
- Accounting platforms
- Billing systems
- Procurement systems
- CRM systems
- Point-of-sale systems
- Tax technology
- Data warehouses
- Document management systems
- APIs and integration tools
The first step is understanding the existing technology environment. A system assessment can identify manual processes, duplicate data entry, integration gaps, outdated systems, data inconsistencies, approval bottlenecks, reporting limitations and control weaknesses, giving management a clearer picture before making technology decisions.
4. Data governance
Good e-invoicing depends on good data. If customer names, addresses, product codes, transaction classifications or accounting information are inconsistent, automation can simply make errors happen faster.
Businesses should consider five areas of data governance:
- Ownership: who is responsible for maintaining invoice-related information?
- Quality: are customer, supplier and transaction records accurate and complete?
- Controls: who can create, modify or approve master data?
- Security: who has access to financial and commercial information?
- Retention: can records be retrieved when needed for reporting, compliance, audit or management review?
Strong data governance makes future digital processes easier to implement and manage.
5. Internal controls
E-invoicing is also an opportunity to review existing financial controls. Businesses should ask:
- Who can create and approve invoices?
- Who can change customer information?
- Who can issue credit notes or make adjustments?
- Are duties appropriately segregated?
- Are changes recorded, and can unusual transactions be identified?
- Are reconciliations performed regularly?
- Can supporting documents be retrieved?
The aim is not to add unnecessary controls, but to make sure the right controls exist around accuracy, authorization, completeness and accountability.
6. Audit readiness
Reliable invoice data also supports audit and review. A connected digital record makes it easier to trace a transaction from the original business activity through the invoice and accounting entry to the financial report.
This can support:
- Transaction testing
- Reconciliations
- Financial reporting
- Tax reviews
- Internal audit
- External audit
- Management reporting
For organizations with high or complex transaction volumes, better data structure can reduce manual effort and improve visibility.
A message from Samer Ali Hasan
“Digital tax transformation is an opportunity for businesses to strengthen the way financial information is captured, managed and used. Preparing early allows leadership teams to look beyond compliance and build stronger processes, better data and greater confidence in their financial information.”
Chapter 3
How Should Businesses Prepare for E-Invoicing?
A practical six-step readiness assessment, and what each member of the leadership team should focus on.
Start with an assessment, not a software purchase
One of the most important decisions for management is where to begin. Businesses should first understand their existing invoicing environment and identify the processes, systems and controls that future e-invoicing requirements may affect.
A practical readiness assessment can follow six steps.
1. Understand the regulatory direction
Monitor official announcements, legislation, executive regulations, technical guidance, implementation updates and communications from the General Tax Authority.
Avoid major technology decisions based only on assumptions or market commentary, and reassess the regulatory position as new requirements are published.
2. Map the invoice lifecycle
Document the complete process, from order and delivery through invoicing, accounting and payment to reporting. Then identify:
- Manual intervention
- Duplicate data entry
- Approval delays
- System gaps
- Reconciliation issues
- Documentation gaps
This gives management a clear view of where improvements may be required.
3. Assess current systems
Review whether current ERP, accounting and billing platforms can support structured electronic invoicing and future integration requirements.
| Area | Key question |
|---|---|
| System capability | Can the platform generate and process structured invoice information? |
| Integration | Can information move between relevant business systems? |
| Scalability | Can the system handle future transaction volumes? |
| Security | Are appropriate access and security controls in place? |
| Reporting | Can management retrieve the information it needs? |
4. Review data quality
Invoice processes depend on accurate master data. Businesses should review:
- Customer information
- Supplier information
- Products and services
- Contract data
- Transaction classifications
- Accounting codes
- Tax-related information
- Bank information
Data cleansing should happen before implementation, not after problems appear.
5. Strengthen controls
Review controls around:
- Invoice approval
- Segregation of duties
- Invoice numbering
- Credit and debit notes
- Adjustments
- Reconciliations
- Access permissions
- Audit trails
- Record retention
The objective is to make sure digital processes remain controlled, transparent and accountable.
6. Build an implementation roadmap
Once the gaps are understood, management can set a practical roadmap covering:
| Workstream | Focus |
|---|---|
| People | Roles, responsibilities and training requirements |
| Process | Redesign manual or inefficient invoice processes |
| Technology | ERP, billing and integration requirements |
| Data | Clean and standardize relevant information |
| Controls | Approval and monitoring processes |
| Testing | Test processes and system integrations before go-live |
| Governance | Clear ownership and ongoing monitoring |
Why should C-suite leaders pay attention?
E-invoicing may sit within the finance function, but its impact extends across the organization.
The CEO
Should understand whether the organization is prepared, and whether implementation could affect business processes, customer interactions or operating models as part of wider digital transformation.
The CFO
Plays the central role in assessing financial controls, tax compliance, reporting, cash flow visibility, data quality, ERP readiness and implementation costs, within the broader finance transformation roadmap.
The CIO
Should consider ERP integration, data architecture, system connectivity, APIs, cybersecurity, data storage, system performance and business continuity.
The Tax Director
Should focus on transaction and tax data, reporting, documentation, record keeping, compliance and regulatory updates.
Internal Audit and Risk
Will find new areas for control testing, data validation, process monitoring, exception reporting, risk assessment and audit trail review.
Digital Tax Administration in Qatar Is Expanding
E-invoicing sits within a broader movement toward integrated digital tax administration. Recent General Tax Authority initiatives include:
- Linking the e-services of the General Authority of Customs and the General Tax Authority, inaugurated in December 2023 (General Tax Authority)
- Launching the Dhareeba mobile application in December 2023, extending the Dhareeba Tax Portal to mobile devices (General Tax Authority)
- Signing an electronic linkage agreement with Edaa in April 2026 to automate data exchange (General Tax Authority)
These developments point to a tax environment in which digital information, structured data and system connectivity matter more and more. For business leaders, the strategic question is therefore not simply whether an invoice can be issued electronically. It is:
Is the organization ready to manage financial and tax information digitally, accurately and consistently?
Frequently Asked Questions
What is e-invoicing?
E-invoicing is the electronic creation and exchange of invoices in a structured digital format, so that invoice information can be processed electronically.
Is e-invoicing mandatory in Qatar?
Not yet. Qatar's Council of Ministers approved a draft e-invoicing law and executive regulations on 6 May 2026, but the law must complete the legislative process and be published before obligations apply. Businesses should verify the latest official requirements, scope and effective dates.
When will e-invoicing start?
No official implementation date had been published at the time of writing. The timeline and applicable requirements should be confirmed against the final law, executive regulations and General Tax Authority guidance.
Does e-invoicing mean VAT is being introduced?
No. E-invoicing and VAT are separate regulatory matters. The General Tax Authority states that VAT has not been applied in Qatar.
Does e-invoicing only affect finance?
No. Because invoice data moves across multiple business systems, e-invoicing can involve finance, tax, IT, procurement, sales, operations, internal audit and senior management.
What should CFOs focus on first?
Understanding the regulatory direction, mapping the current invoice lifecycle, identifying data and system gaps, and establishing a cross-functional readiness plan.
Does e-invoicing require an ERP upgrade?
Not necessarily. The right approach depends on the existing ERP, accounting and billing environment, future requirements, transaction volumes and integration needs. A system assessment should come before any major technology decision.
Can e-invoicing improve financial controls?
It can, when supported by appropriate systems and controls. E-invoicing is an opportunity to strengthen invoice workflows, approvals, audit trails, reconciliations and data consistency.
How can businesses improve e-invoicing data quality?
By reviewing and standardizing customer, supplier, product, service, transaction and accounting data before implementation, and by assigning clear data ownership and controls to maintain quality over time.
Summary
Tax e-invoicing is becoming an important part of Qatar's digital tax transformation. With a draft e-invoicing law approved by the Council of Ministers and further details still to be confirmed, businesses should look beyond invoice generation.
The businesses best placed to respond will be those that have already reviewed their invoicing processes, technology, data and controls, and that treat e-invoicing as part of a wider finance and governance agenda rather than a system change alone.
CLA Qatar — Local expertise. Global perspective.
Talk to CLA Qatar About E-Invoicing Readiness
Understand your current position. Assess your readiness. Plan your next step.
Article references
Open article reference Close article reference
- Qatar General Tax Authority — Qatari-Russian cooperation to promote digitalization and e-invoicing in tax
- Qatar General Tax Authority — Taxes Information
- Qatar General Tax Authority — Investors Guide
- Qatar General Tax Authority — Interconnection between the customs and tax authorities
- Qatar General Tax Authority — Electronic linkage agreement with Edaa
- Qatar General Tax Authority — Dhareeba application launch
Contact
For further information
CLA Qatar Tax & Accounting Services
Speak with our team about e-invoicing readiness, tax compliance, finance systems, data governance and financial controls in Qatar.
- E-Invoicing Readiness
- Tax Compliance
- ERP & Systems Review
- Data Governance
- Internal Controls
- Audit & Assurance
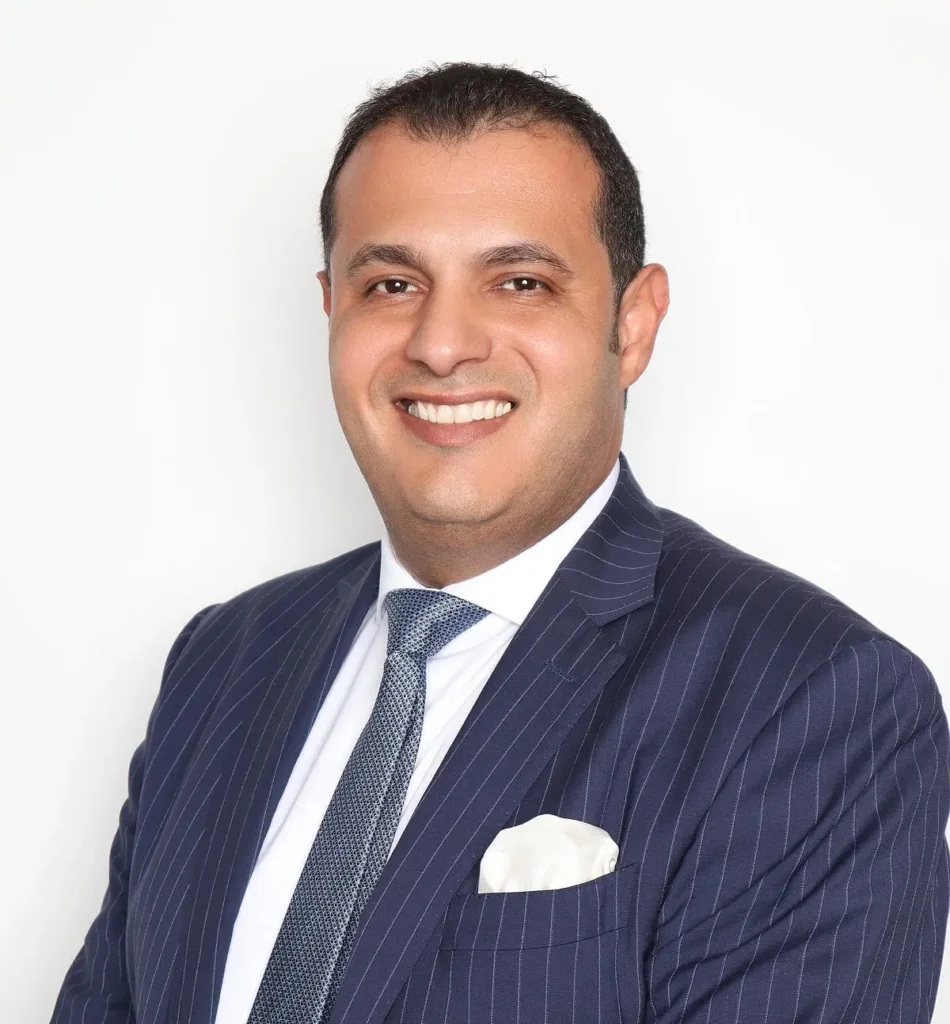
Samer Ali Hasan
CEO & Managing Partner, CLA Qatar